
The lender said this was launched due to borrower demand for more flexibility, as it allows borrowers who may not meet mainstream residential mortgage affordability criteria but still have income to make monthly payments.
Pure Retirement will give borrowers a discounted interest rate for making monthly payments of at least 25% of the monthly interest.
Borrowers can stop making monthly payments at any time and this will end the interest rate discount. The feature also allows borrowers to take payment holidays of up to three months each year, and make optional partial repayments of up to 12% each year of the amount borrowers without any early repayment charges (ERCs).
The Emerald range also includes a seven-year fixed ERC period and no upfront initial loan fees.
Pure Retirement said the update followed its recent research, which showed 92% of borrowers who had a product with interest servicing said the feature was the main reason or an important factor in choosing the product.

Grasping the next buy to let opportunities
Sponsored by Aldermore
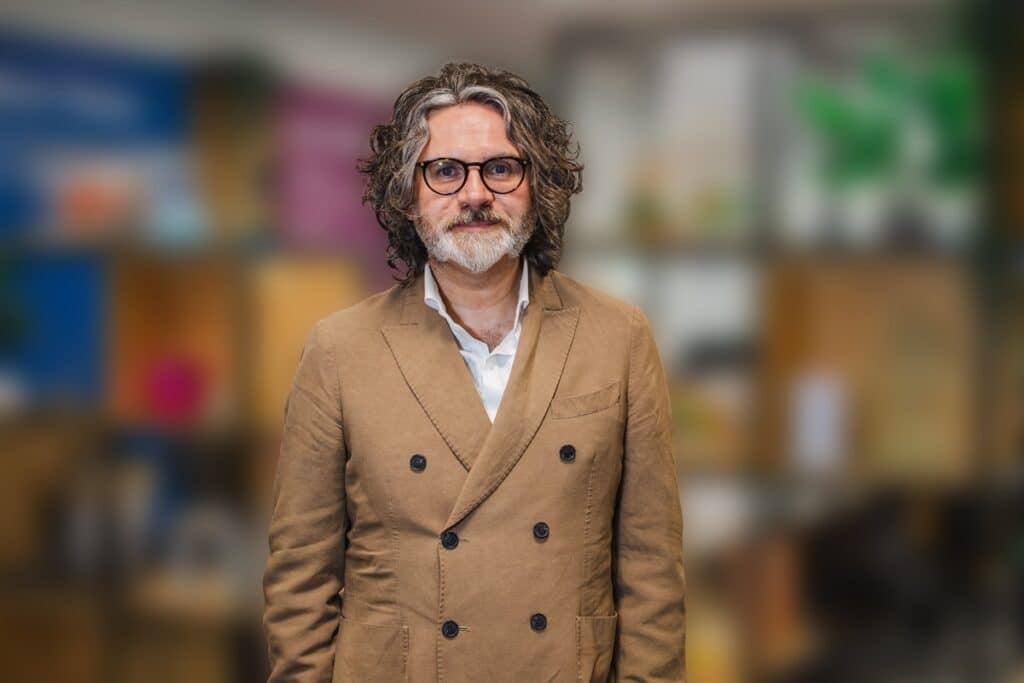
Simon Hayton (pictured), managing director of Pure Retirement, said: “Mortgage advisers are likely to have clients for whom a mainstream residential mortgage is no longer available or suitable, who are unable to evidence a capital repayment strategy, or who expect their income to reduce before the end of the mortgage, for example at retirement.
“If advisers are not considering interest servicing lifetime mortgages as part of the later life lending conversation, they may be missing an important option for clients who still have some income and a preference to make monthly payments. Interest Servicing on Emerald has been designed to support those conversations and provide greater flexibility for customers who may have fewer borrowing options.”