
The group also grew its mortgage book by 6.9% to £32.2bn, which it said was “materially faster” than the rest of the market.
It supported 12,322 first-time buyers during the period, an increase from 9,756 last year, and half of its lending was to new homeowners, up from 43% previously.
Skipton said it was committed to making homeownership a reality for people, adding that its recently launched Delayed Start mortgage – which allows people to purchase without repaying the mortgage for the first three months – had received “excellent feedback” and had 151 applications in its first month.
Its estate agency subsidiary Connells saw profitability improve, with a profit before tax of £28.4m, up from £20m previously. It attributed this to activity recovering in the housing market, buoyed by purchases before the stamp duty changes in April.
Skipton International reported an “anticipated” lower profit before tax of £6.8m, down on £18.2m last year. This was because of a strategic slowdown and external market factors, reducing the returns on mortgages.
Episode 5: Larger Loans and Complex Lending: Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
Skipton Building Society delivered a profit before tax of £101.1m, down from £113m in 2024. It said despite its net interest margin performing better than last year, its investment and increases in loan impairment impacted its profit.
Across the group, the rate of UK residential mortgages in arrears of three months or more made up 0.32% of its book, slightly up from 0.27% last year.
The group’s profit before tax came to £135.1m, compared to £157m the year before, with the lower figure attributed to higher staff investment and impairment charge.
Its net interest margin “benefitted from favourable cost of funds”, rising from 1.27% to 1.3%.
A ‘strong performance’ for Skipton Group
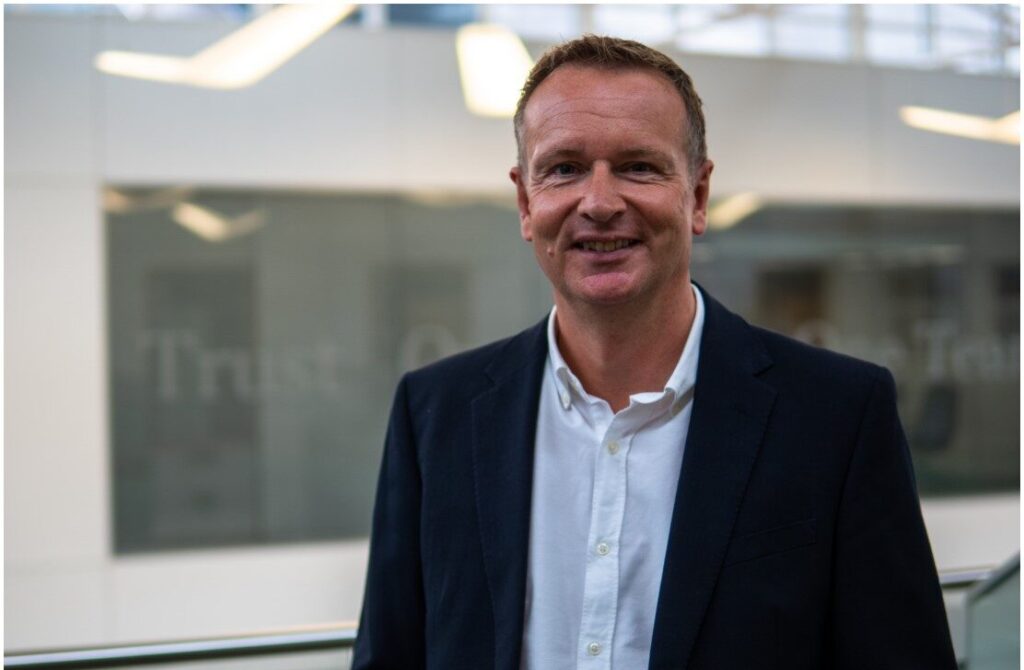
Stuart Haire (pictured), group chief executive at Skipton Group, said: “I am delighted to share details of our strong business performance in the first half of 2025. We are growing faster than the market, supporting our members and customers with quality products and services, maintaining strong capital growth and delivering against our purpose through innovation and challenging the status quo.
“Our group purpose is to help people have a home, save for life ahead and support long term financial wellbeing. It remains as relevant today as it was in 1853 when the society was founded.”
He added: “Against an uncertain backdrop, we are delivering against our strategic priorities, and driving meaningful change on socially important matters, by finding new ways to use our collective group insights to better support our members in achieving their long-term financial wellbeing. As the government continues to advocate for increasing the growth, relevance and development of the mutual sector, we are ready to share the benefits of membership with more people across the UK.
“None of what we have achieved would be possible without our people, and I would like to thank each and every one of my colleagues across the group for their dedication, drive and unwavering focus on delivering for our members.”