
The lender will now indicate whether an eligible property is acceptable security before a full mortgage application is submitted.
Under the new process, where a property meets the lender’s criteria at DIP, Gen H’s platform will provide an initial property approval.
Provided the property details remain unchanged throughout the application, underwriters can rely on the AVM, meaning a successful DIP can serve as a strong indication of a full underwriting approval.
Typically, lenders only carry out a valuation once a full mortgage application has been submitted and a hard credit search has been completed. If a property does not meet the lender’s requirements, borrowers may then need to find an alternative property or apply elsewhere.
By introducing AVMs at the DIP stage, Gen H said it aims to give brokers and their clients greater confidence earlier in the application process.
Episode 4: New Build: Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
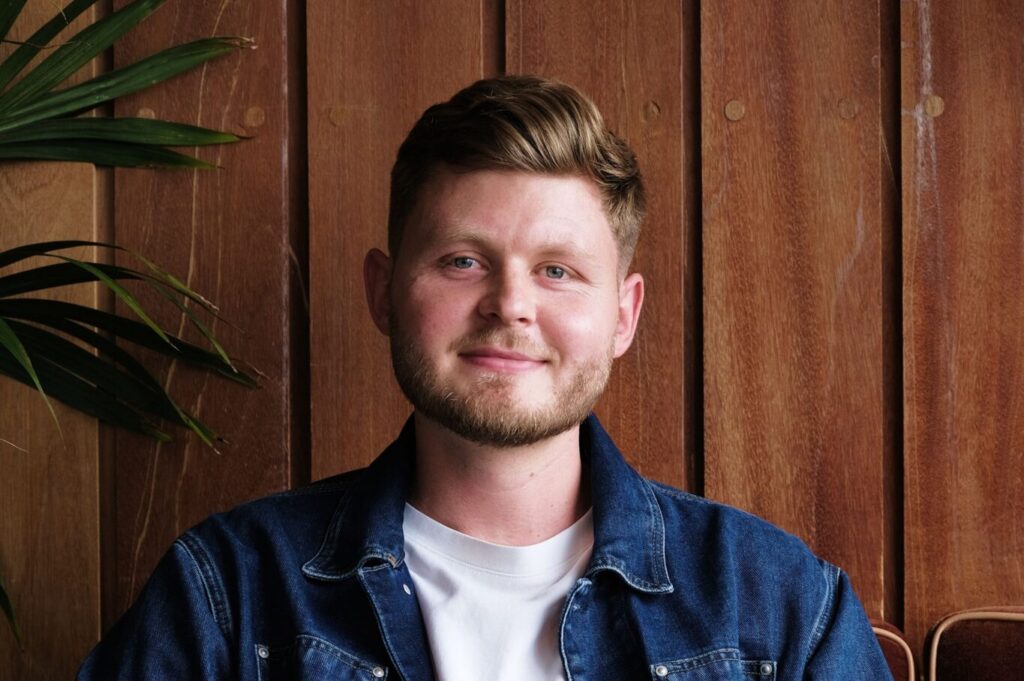
Luke Calton (pictured), head of product at Gen H, said: “We know that getting certainty as early as possible is top priority for our broker partners. Property decisioning was the missing piece to reaching a fully automated ‘yes’ at DIP, so we’re delighted to launch this new feature.
“We’ve built our systems from scratch, which means we can easily and immediately prioritise new quality-of-life improvements based on broker feedback. This was a popular request, and we’re looking forward to seeing how this new feature will make our brokers’ jobs easier.”