

Mortgage News
Buy-to-let lending up 32% this year

Lending to property investors rose 32% year-on-year, but remains at just a third of pre-credit crunch levels in 2007.
CML Q1 figures showed new buy-to-let lending of £3.7bn or 32,300 loans, which is 5% down on the final quarter of last year.
The buy-to-let sector continues to increase its share of the mortgage market, with buy-to-let mortgages at an estimated 12.8% of the total value of outstanding mortgages at Q1.
The total number of buy-to-let mortgages stands at just over 1.4m with a total value of £159.4bn.
The average maximum loan-to-value for buy-to-let mortgages in Q1 was 75% with minimum rental cover at 125%, which has held steady for three years.
Arrears on BTL at 1.7% remain lower than the owner-occupied sector at 2%. Repossession levels at 0.12% were higher than residential at 0.8% as lenders practice less forbearance with struggling BTL investors.
Episode 2: Affordability : Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
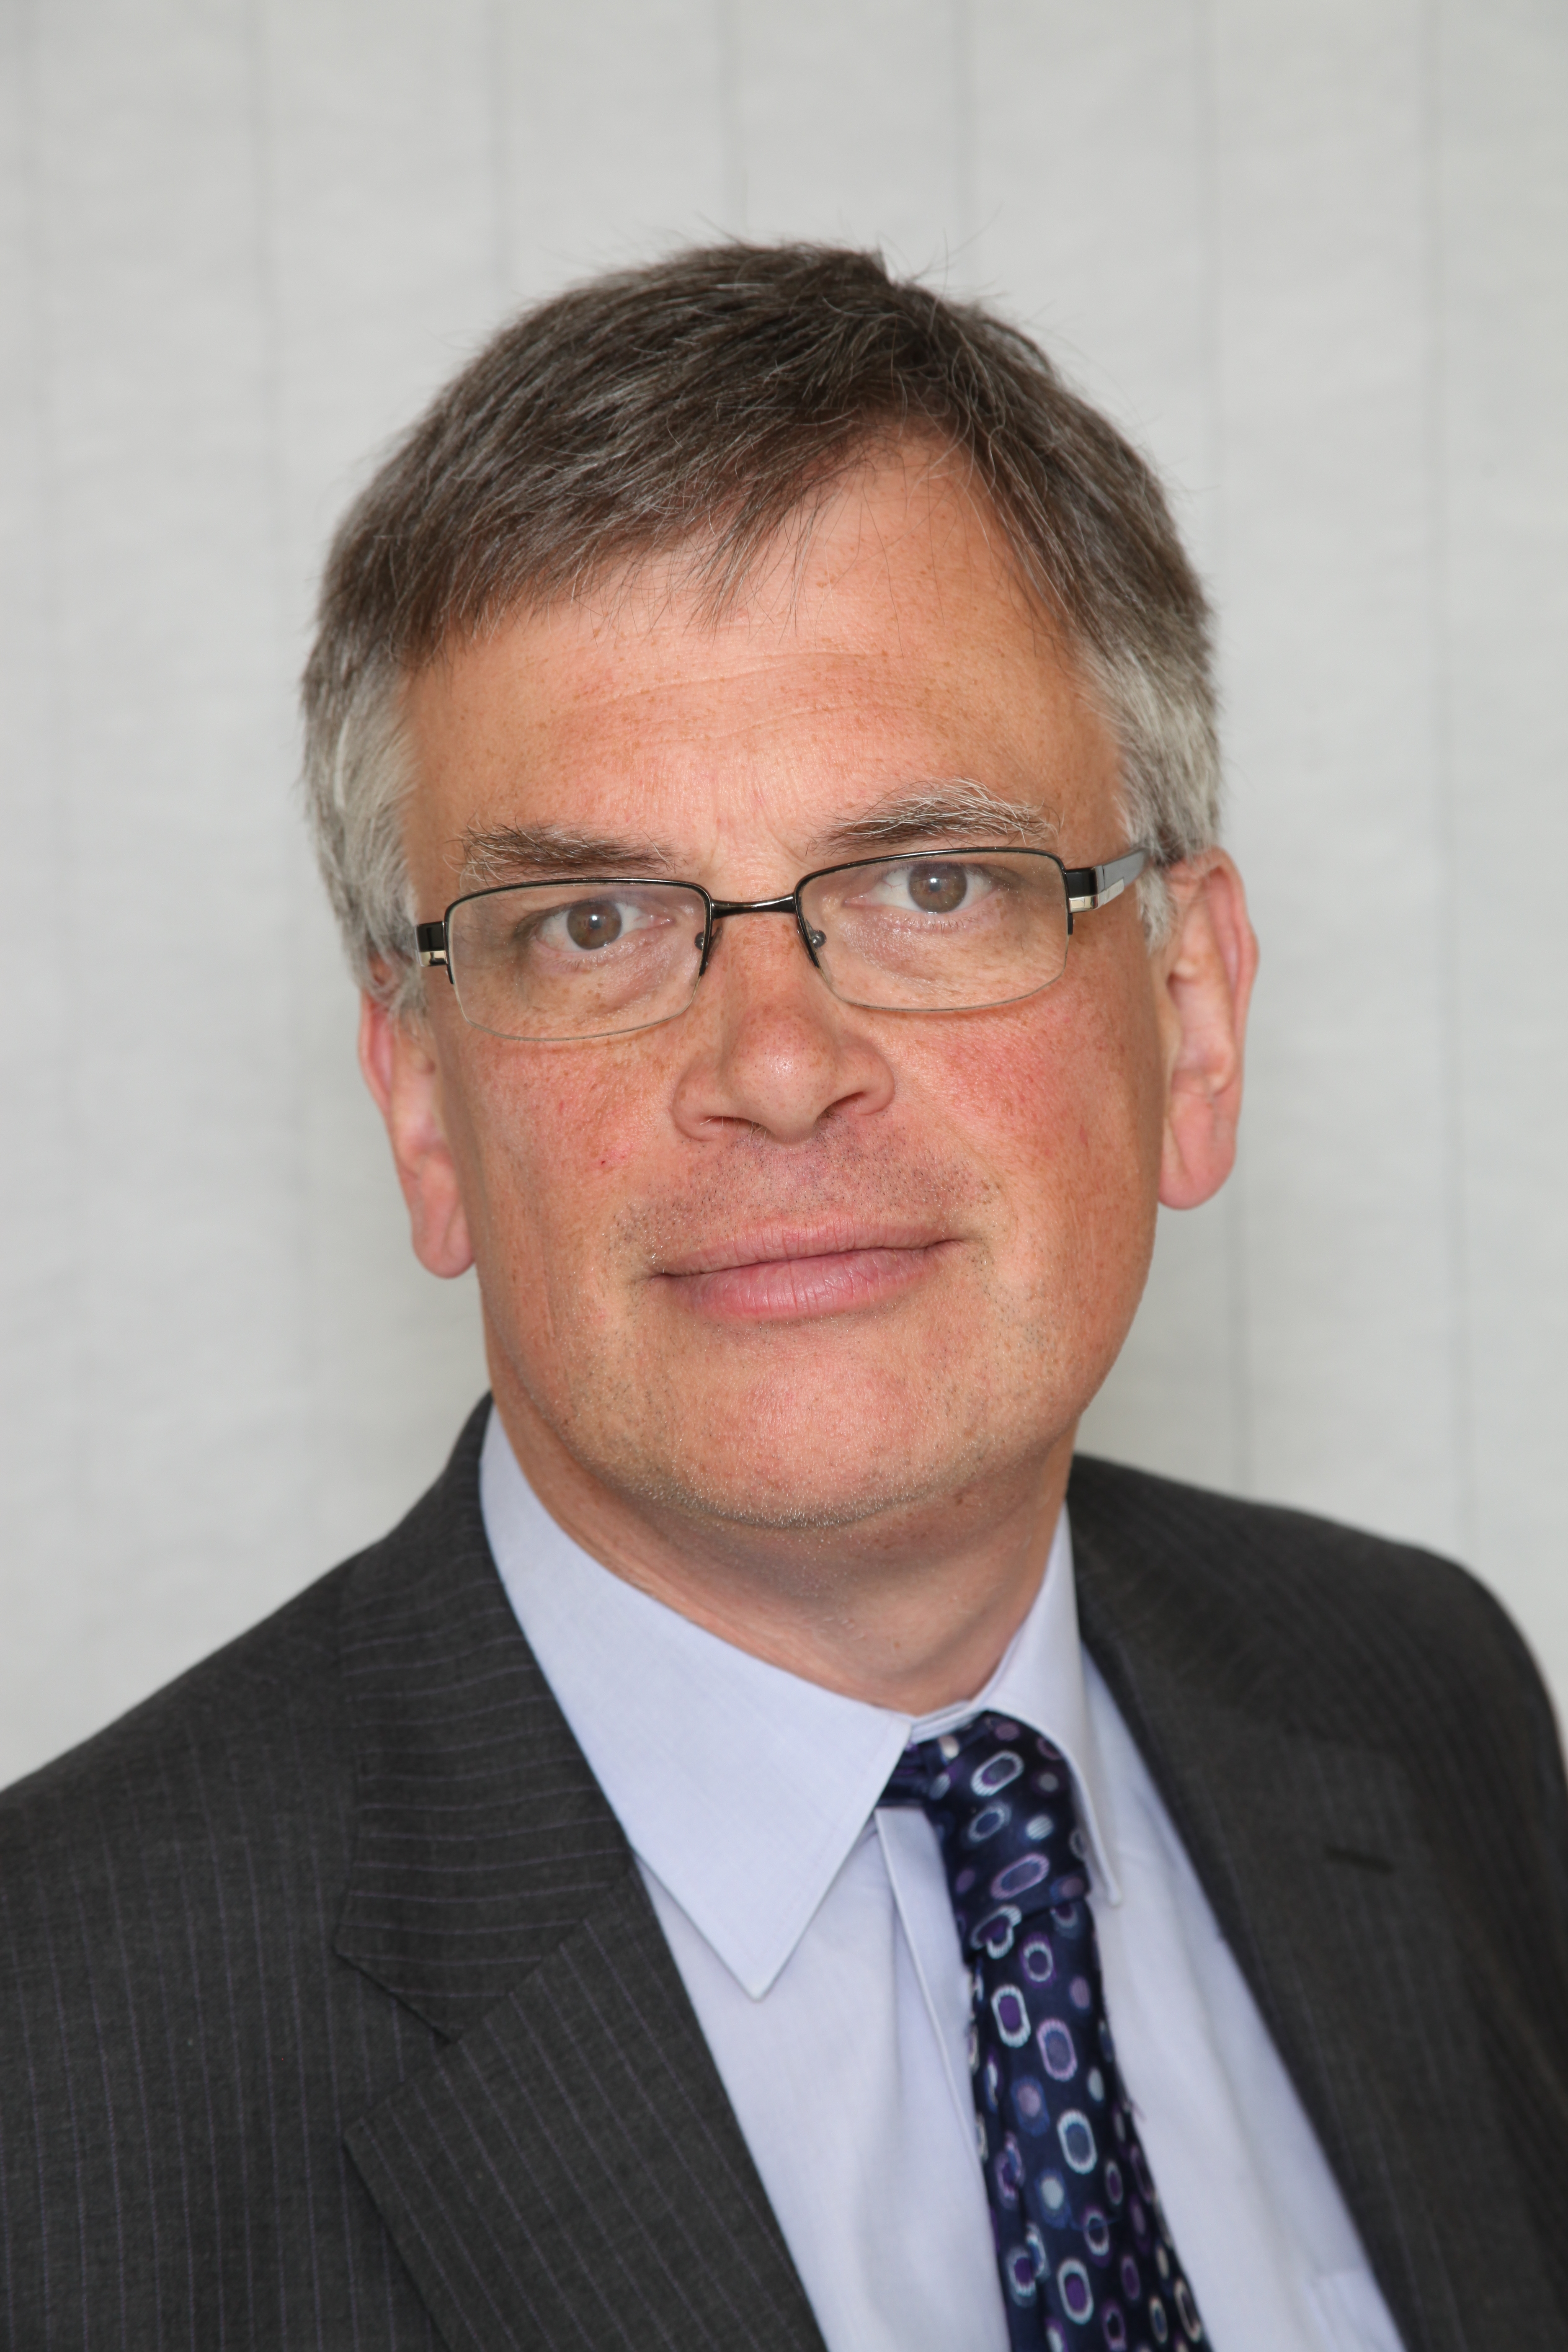
CML director general Paul Smee (pictured) said: “Even though buy-to-let lending is running at only around a third of its peak levels, the sector is continuing its gradual expansion. It has become an important part of the overall landscape of housing provision in the UK.”
Meanwhile, the CML said it could revise down its 45,000 arrears projection later this summer as overall arrears figures improved slightly. In Q1, the number of mortgages with arrears of 2.5% or more of the balance fell to 157,800, or 1.4% of all loans.
Borrowers 10% or more behind on the total balance on their mortgages are the only tier to have risen, if only by 300 against 2011 figures.
However, continuing pressures on household finances, changes to welfare benefits, and an upward drift in mortgage rates all have the potential to disrupt the current stable picture, said the CML.
Mark Blackwell, managing director of xit2, the property and mortgage data specialist, said: “Repossessions orders flowing through our systems in April fell 12.5% from the Q1 average, suggesting lenders are becoming even more tolerant of borrowers in long-term arrears – at least for the time being. But they can’t go on doing it forever.”
Banks funding costs are increasing and their balance sheets are being stretched, so there will come a point where lenders will reassess, said Blackwell.
“With the economy stalling, and the crisis in the eurozone worsening, that point may well come later in the year. We could see swathes of borrowers in long term arrears pushed over the edge once lenders turn off the forbearance packages that are acting as life support machines for borrower finances,” he said.
Repossessions by second-charge mortgage providers fell by 19.5% in Q1 2012 against Q1 2011, in other figures.
The Finance & Leasing Association (FLA), the trade body for the second-charge mortgage market said its members repossessed 157 properties in Q1.