
The group closed the year with a revenue of £318.8m, up from £266.5m the year before, while its growth profit rose from £77m to £91.9m. The group said this reflected its focus on productivity and the measured expansion of its adviser base.
Income from proc fees rose 27% to £133.9m year-on-year as advisers capitalised on higher refinancing activity.
Product transfers made up 24% of the 166,000 mortgages transacted by MAB in 2025, up from a share of 22% in 2024. Remortgages accounted for 24% of business, down from 25% the year before, while purchase activity made up 51% of activity, compared to 53% in 2024.
Overall, MAB facilitated 18% more mortgages than the year before and there was a 4% increase in the average mortgage size.
Its market share for new mortgage lending was stable at 8.4%, while its total mortgage market share grew slightly from 5.7% to 5.8%.
Episode 2: Affordability : Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
Further, MAB saw a 12% increase in income from protection and general insurance, coming to £117.5m. This included a 13% rise in commission for pure protection, totalling £102.7m, while commission generated from general insurance rose 4% to £14.8m.
There was a 20% rise in income from client fees, totalling £61.3m. Some £29.1m of this came from first charge mortgages, up 12% annually, while £32.2m was from specialised lending, a 28% rise.
Advisers generate higher revenue
MAB reported a growth in adviser productivity in 2025, with the average revenue per mainstream adviser rising 13% to £157,000. The group said this was significant, as many new joiners would not reach full productivity until 2026.
The group welcomed 2,135 mainstream advisers to the business, bringing its adviser numbers up 10% on the year before. It said 65% of this growth was driven by the organic expansion of firms already part of MAB’s network and was the first year of material growth since 2022, pointing to improved confidence.
Revenue across its appointed representative (AR) network was 17% higher at £177.7m, while revenue from MAB’s invested businesses increased 23% to £141.1m.
The 1,463 advisers within its AR network generated £122,000 in revenue on average, up 15% on the year before, while the 568 advisers within its invested businesses produced an average revenue of £248,000 each, up 4%.
MAB said all of its revenue growth was organic as its merger and acquisition activity focused on consolidating existing investments, which contributed £5.4m of additional gross margin.
Gross profit from its AR network increased by 11% to £44m, but the profit margin contracted from 26.1% to 24.8% due to changes in the business mix, primarily the growth in product transfers and remortgaging.
Gross profit from its invested businesses increased 31% to £53.8m, while the margin improved from 36% to 38.1%.
MAB to focus on AI, home moving process and M&A opportunities
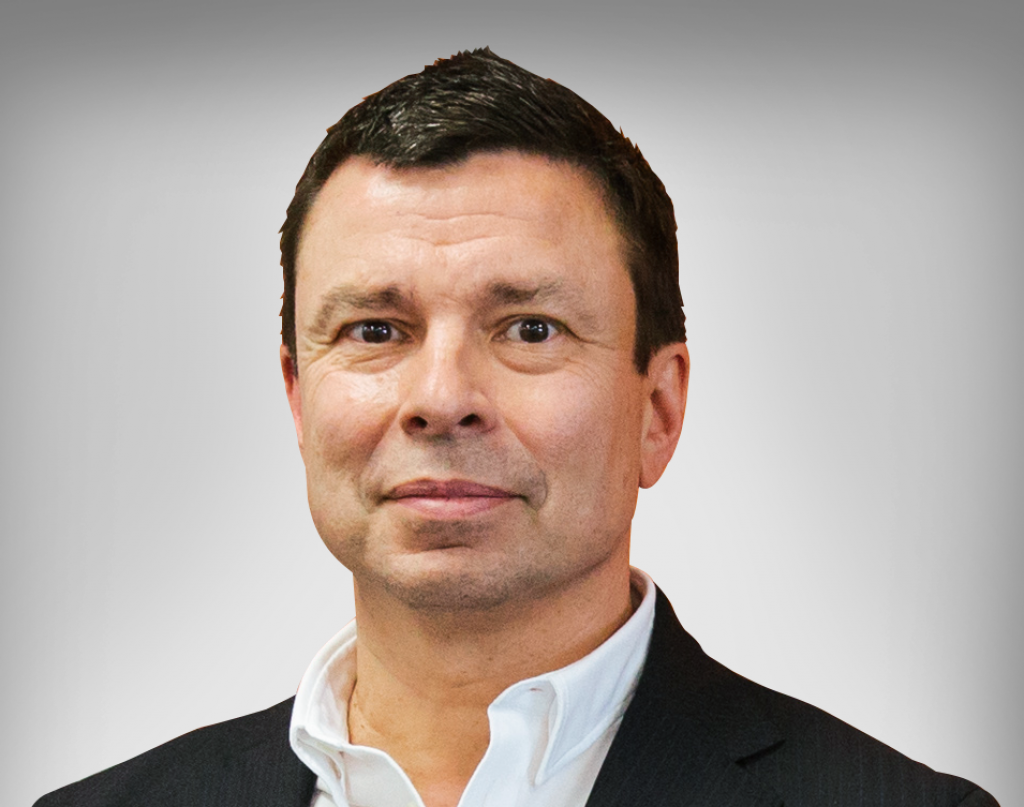
Peter Brodnicki (pictured), founder and chief executive of MAB, said 2025 was “another year of strong performance” and the business was on track to deliver its five-year growth plan.
He said MAB had become “uniquely positioned in the intermediary and mortgage sectors as a result of executing a very deliberate strategy to build a specialist network with customer acquisition at the heart of the model”.
Brodnicki added that because the group continued to invest, its customer reach now extended across estate agency, new build, price comparison websites, credit bureaus, property portals and employers, delivering sustainable growth and an ability to stay stable during market downturns.
Brodnicki said: “We’re now starting to leverage data, digital tools, and artificial intelligence (AI) to deepen relationships with introducers, lenders, and consumers and unlock significantly more lead flow. At the same time, these capabilities are helping us retain more existing customers and engage a much wider audience of early researchers, helping them understand their options and become mortgage-ready.
“MAB has become a leading, tech-driven intermediary platform at the heart of mortgage and protection advice today, with the business ideally positioned to harness developments in AI to further extend its reach, performance and efficiency.”
He added: “We are still in the relatively early stages of AI adoption, but the potential is significant. Combined with our customer reach and data assets, AI will help us further improve performance and efficiency, delivering an exceptional, hyper-personalised customer experience, scaling, and increasing margins and supporting growth and margins.
“Advice will remain central to our model, but the way it is delivered will continue to evolve. Some customers prefer a lighter digital-first approach, while others need deeper adviser involvement for more complex decisions. Our model flexes accordingly.”
Looking ahead, Brodnicki said MAB was building “new strategic partnerships” and “pursuing selective mergers and acquisitions” to expand its role in the home moving process, widen its proposition and add value for its customers ahead of the government’s changes to the transaction process.
“Through continued organic growth, disciplined acquisitions and the increasing use of technology, data and AI, we believe MAB is well-positioned not just to participate in the mortgage market, but to shape where it goes next,” he added.