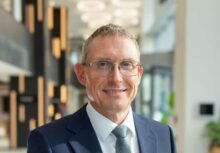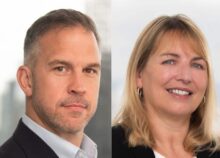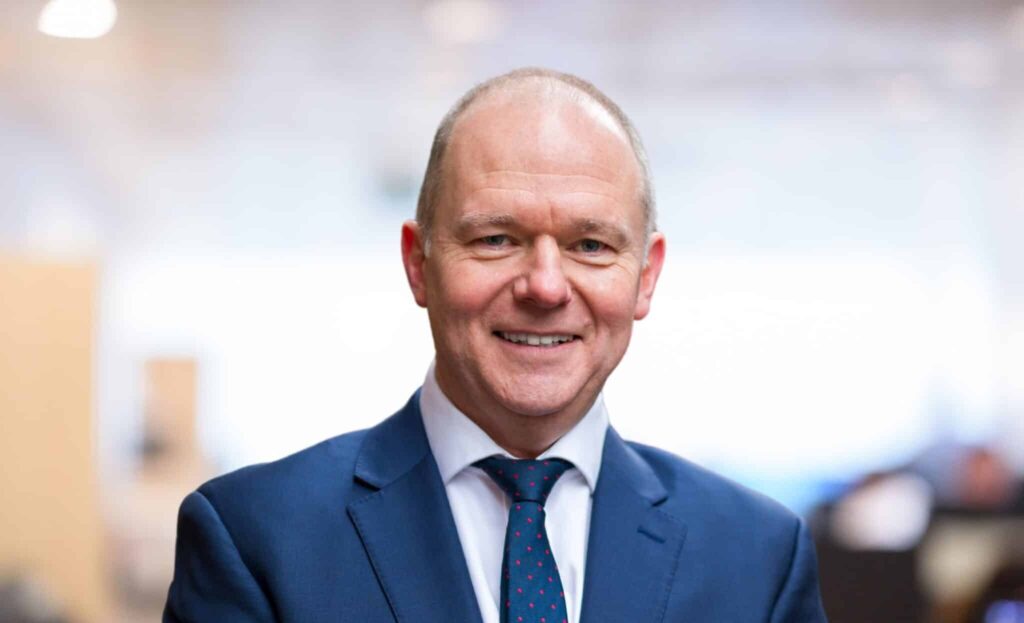

Andy Thomson (pictured), senior director of operational real estate, was brought in two months ago to focus on the UK living sector, which includes BTR, a major focus for the bank in 2025. With the support of Paul Turton, director of business development and marketing for property, the team are targeting mid-market BTR developers and investors in need of finance for projects in England, Wales and Scotland.
And Turton said brokers are integral to the success of the expansion.
As well as the established and dominant multi-unit end of the market comprising multiple apartments in a single block, UTB is also targeting the newer end of the BTR sector – single-family homes.
“A lot of the housebuilders have been left with surplus stock and are keen to get that sold and get the cash onto the balance sheet, so there’s been some quite large transactions [in this market].
“Investors really like [single-family homes] because, unlike the large apartment blocks where tenants tend to stay for a year or 18 months, in more traditional housing, tenants tend to stay around for between five to seven years.
Episode 5: Larger Loans and Complex Lending: Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
“The less churn [of tenants] there is, the more money investors will make from the properties,” he said.
BTR lending ambitions
To date, UTB has lent £1.3bn to bring forward build to sell and rent housing, and currently it is funding the construction of 4,500 homes.
Turton said: “We want to grow that overall book. Our customers want to pivot into that [BTR] sector and we will follow our customers, plus the new customers we’re onboarding.”
With loan sizes ranging from £10m to £35m, the bank is able to support the development of BTR sites ranging from around 100 units in outer London and around 200 units in the regions.
Thomson said: “We’d call this the mid-market; we’re not going out to do the deals where someone wants to build 500 or a thousand units. We’re somewhere in the middle, which is [a] good hunting ground for us.”
This mid-market strategy means UTB targets regional housebuilders and “opportunity-led” entrepreneurial developers that focus on conversions to rent out, for example.
The bank provides four products for the BTR market: a two-year development loan for ground-up projects or the conversion of offices to residential units or hotels into co-living, a stabilisation loan offered at completion allowing developers to get the units let, an investment loan to buy fully let income producing sites, and a loan that combines all three stages.
Building up the customer base
Thomson said: “To get our products out into the market, we’re using a multi-pronged attack to widen distribution.
“We’ve got a fantastic existing customer base. For example, I was up in the Midlands during the week meeting [a] UTB client [to whom] we are currently providing a loan to build up around 20 houses, and they’re interested to hear what we can do on the rental side once they are built. Next, they want to build 150 build to rent apartments.”
He added: “We’ve also got a lot of good-quality broking relationships. Brokers are an important part of our business and distribution model.”
The bank is also establishing new relationships through social media advertising and its website.
Challenges and opportunities for the 2025 BTR market
At the start of its expansion, UTB is well aware it is facing multiple headwinds. Geopolitical uncertainty, the war on Ukraine and the actions of the US all have a ripple effect on the real estate market because they create uncertainty, Thomson explained.
At the same time, construction costs and inflation have been high over the last few years and the availability of skilled labour in the UK has been low. All these events have occurred against a backdrop of much higher interest rates.
However, Thompson is optimistic about the outlook for the BTR market in 2025, following Savills’ 2024 market update, which reported record levels of investment into the sector, exceeding £5m for the first time.
Furthermore, the government’s housebuilding plans and changes to planning policy to make it easier for projects to be built out are a win for the sector, he said, along with the prospect of lower interest rates this year.