user.first_name
Menu

Sponsored content

Your First Home: confidence to build

Halifax Intermediaries
Your First Home: confidence to build
Andy Dean
Written By:
Posted:
October 15, 2026
Updated:
October 15, 2026

Your First Home could open the door for more first-time buyers, while giving builders greater confidence to invest in the new homes we need, says Andy Dean, head of housing development & sustainability, Lloyds Banking Group

For many aspiring homeowners, saving a large enough deposit while paying rent is the barrier that keeps homeownership out of reach. The newly announced ‘Your First Home’ scheme could help overcome it.
The government’s proposed equity loan scheme is intended to support first-time buyers purchasing a new-build home in England. Buyers will need a minimum 2.5% deposit, with a 20% government equity loan and a mortgage covering the rest.
New build won’t suit every first-time buyer, but it can offer more certainty from day one. There’s no onward chain, homes come with warranty protection and new fixtures and fittings, and better energy efficiency can help keep running costs down.
The Home Builders Federation’s Watt a Save research found that new-build homes use around 30% less energy than the average older property. For a first-time buyer already stretching to cover a deposit and moving costs, lower bills and fewer immediate repairs can make a meaningful difference.
But, while the scheme has obvious benefits for buyers, its impact could reach much further.
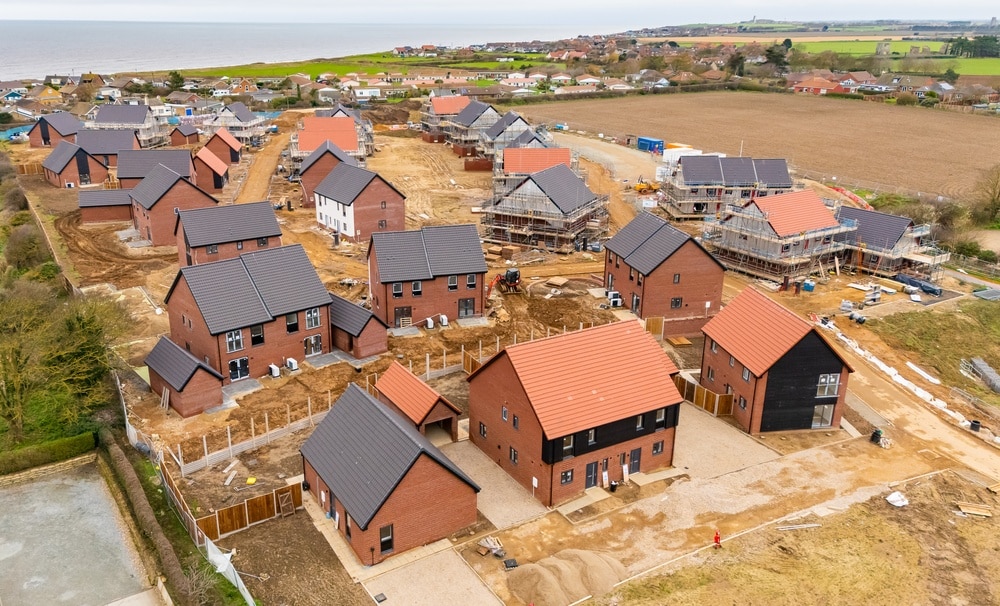
In a subdued market, home builders need confidence that new homes will sell before committing further investment. Planning, land, infrastructure, skills and viability all affect how many homes are built, but demand matters too. If builders aren’t confident that homes will sell, planned developments are less likely to move forward at the pace we need.
The challenge is visible in current sales rates. The latest Home Builders Federation (HBF) Housing Market Intelligence report shows that average sales by major housebuilders have fallen from more than 0.8 homes per outlet each week in 2022 to 0.56, with rates below 0.3 for the smallest developers. That matters because slower sales reduce the confidence and capacity to invest in new sites and increase delivery.
And housebuilding delivers benefits well beyond additional supply. The HBF estimates that the 209,000 homes delivered in England during 2024/25 generated £46bn of economic activity, supported 734,000 jobs and contributed £1.3bn towards infrastructure, including around £600m for schools.
Lessons from Help to Buy

The recently published government evaluation of the Help to Buy scheme suggests that supporting buyers can give developers greater confidence and lead to more homes being built. It estimates that around 15% of the new homes built in England while the scheme operated were attributable to Help to Buy, with the impact on developer confidence strongest in its earlier years.
It also offers useful lessons for Your First Home. The evaluation found that Help to Buy delivered very high value for money and helped some buyers purchase sooner than they otherwise could have. Nearly half of customers said they would not have been able to buy without the scheme. There was some evidence of modest price increases in less affordable areas, although these varied by location. The proposal to restrict the new scheme to first-time buyers, and apply income limits and local property price caps, reflects the desire of the government to target support carefully.
Clear communication will be just as important. Most Help to Buy customers had a positive experience, but some were unclear about the equity loan and repayment process. An equity loan is not a grant, so buyers need to understand from the outset what happens when interest becomes payable or they want to remortgage, sell or repay it.
We know the broad outline of Your First Home, but important details are still to come. Sharing them quickly will help buyers, brokers, lenders and builders prepare, and reduce the risk of buyers putting decisions on hold while they wait to find out whether they qualify.

Encouraging buyers to explore their options

Your First Home will offer just one route, and won’t provide the answer for everyone, and it applies in England rather than across the UK.
Depending on where they live and their circumstances, first-time buyers may have other mortgage, shared ownership or government-backed options. Some will be better suited to a standard high loan-to-value mortgage, while for others, Shared Ownership or First Homes may be a more realistic route.
Your First Home could also encourage people who had assumed homeownership was beyond their reach to take another look, and you can help them. You don’t need an established relationship with a housebuilder or a desk on a development to support these clients.
Brokers can explain what may be possible, compare the upfront and longer-term costs of the available routes and help clients make a well-informed choice. Understanding the scheme will therefore be important even if it turns out not to be the right answer for that particular buyer.

Building on what works

Lloyds Banking Group has supported first-time buyers, new-build clients and government-backed routes into homeownership for many years and has extensive experience of new-build lending.
We understand that these cases can bring different timescales, criteria and processes, and we’ll work with brokers as the detail of Your First Home becomes clearer.
We welcome what the scheme is trying to achieve and the confidence it could give buyers and builders. We now want to understand the detail and what it will mean in practice for clients, brokers and the wider market.
The opportunity is clear. If Your First Home helps more people see a realistic path to homeownership, gives builders the confidence to invest and creates more opportunities for brokers to support aspiring buyers, it will have made a real difference.

For the use of mortgage intermediaries and other professionals only

The information contained in this article is the property of Lloyds Banking Group plc and may not be reused or publicised without our prior permission. The information provided is intended to be for information only and is not intended to be relied upon. This information is correct as of October 2026. If you do not have professional experience, you should not rely on the information contained in this communication. If you are a professional and you reproduce any part of the information contained in this communication, to be used with or to advise private clients, you must ensure it conforms to the Financial Conduct Authority’s advising and selling rules.

Halifax is a division of Bank of Scotland plc. Registered in Scotland No. SC327000. Registered Office: The Mound, Edinburgh EH1 1YZ. Bank of Scotland plc is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority under registration number 169628.

Privacy Preference Center