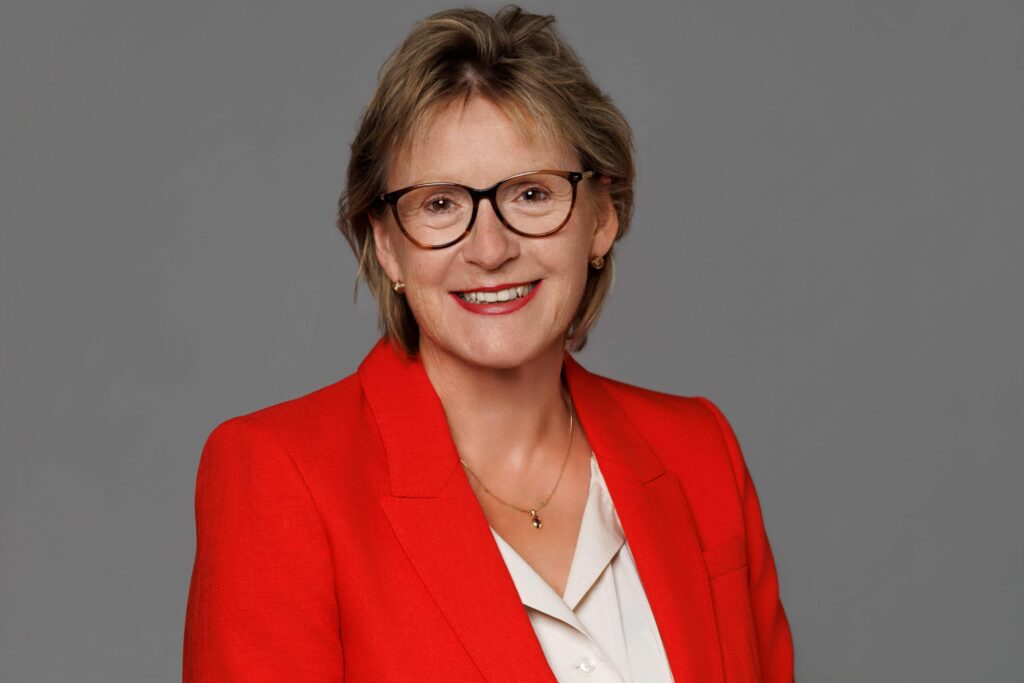

This month features Sarah Harrison, chief executive of the Building Societies Association (BSA).
Your career has taken you through government, regulation and consumer protection. What drew you to the building society sector and the role of BSA chief executive?
I have spent much of my career in roles where public purpose, consumers and complex change come together. I have worked in government, regulation and, most recently, the Cabinet Office. Those experiences taught me how institutions earn trust, how regulation affects people in practice and what it takes to turn a good idea into meaningful change.
The BSA role brought those threads together. I grew up in a family farming business with roots in the cooperative movement, so member and customer ownership has always felt natural to me.
Building societies help people do some of the most important things in life: buying a home, building savings or becoming more financially secure. I find that clarity of purpose and outcome very powerful. I was also attracted by the opportunity. Building societies already make a substantial contribution, particularly to support first-time buyers and customers who are underserved by the wider market, yet they have the potential to reach many more people and show why customer ownership is even more relevant today.
Episode 5: Larger Loans and Complex Lending: Powered by Partnership podcast from Newcastle for Intermediaries
Sponsored by Newcastle for Intermediaries
You have held senior leadership roles through periods of considerable change. What is the most important lesson you have learned about leading people?
The biggest lesson is that leadership starts with listening. Experience and ideas are valuable, but first you need to understand the people, the organisation and the context. Since joining the BSA, I have spent time with our members across the UK, hearing about their ambitions, the pressures they face and the communities they serve.
Good leadership also requires clarity. You need to set a direction, invite challenge and be prepared to make decisions. I enjoy bringing people together around a shared purpose and giving them the confidence to contribute. This was very much the approach used to shape the BSA’s new strategy for sector growth – Finance for a Fairer Future – which we published in July.
You joined the BSA in December 2025. What has surprised you most about the sector, and what significant changes have you seen in the mortgage market since?
What has struck me most is the sector’s openness and genuine willingness to share. That is one of its superpowers and one I think building societies and credit unions can turn increasingly to their commercial advantage.
The market itself has certainly not stood still. Most recently, the conflict in Iran and the resulting volatility in financial markets have been a reminder of how quickly the outlook for mortgage rates can change. For borrowers, that creates uncertainty at the very point they are trying to make one of the biggest financial decisions of their lives. For brokers, it means an even more important role in helping customers understand their options and navigate a market that can move very quickly.
Affordability remains a defining challenge too. Customers’ circumstances are increasingly varied, whether that is irregular income, different household structures or careers that do not fit neatly into a standard application.
Building societies have a long history of looking at the person behind the numbers, considering individual circumstances and taking a more rounded view of affordability. That ability to exercise judgement, rather than simply relying on an automated decision, will remain hugely important.
The government’s ‘Your First Home’ scheme could create another route into homeownership. Societies and brokers will be crucial to making it work, not simply by helping customers access the scheme, but by identifying when another mortgage product or route to homeownership is more suitable for their circumstances and needs. Good advice is about finding the right solution, not simply the newest or highest profile one.
If there were one thing you would like the wider mortgage market to understand better about building societies and the BSA, what would it be?
That mutuality isn’t just about heritage. It is a competitive advantage.
Customer-ownership and being based in the regions and nations of the UK gives building societies and credit unions the freedom to think long term, innovate around genuine customer needs and compete in parts of the market where a more individual approach can make a real difference.
The BSA’s role is to help turn the strength of individual societies into collective impact, creating the conditions for the sector to grow, innovate and serve more people.
This isn’t a sector to turn to only when the mainstream says ‘no’. Building societies are ambitious for growth and competing for business. So, my message to brokers is simple: think again about building societies, because there may be more options for your clients than you realise.